Problem first — why this matters
Many people in Singapore and beyond hit the same snag: revolving credit balloons during income dips, but payday or high-interest credit cards make it worse. Using didi prestamos as a short-term bridge sounds practical — and sometimes it is — but must be done correctly. I’ve seen this since the 2020 downturn when job losses forced quick fixes and regulators like MAS warned about risky borrowing; this real-world stress test shows the choices matter. Also consider how a separate product like didi credito might fit into your cash plan before you borrow.
Root problems people miss
Common issues are simple: mismatch between loan tenor and cashflow, underestimated APR and fees, and poor credit utilization control. Revolving credit compounds when you only pay minimums; interest rate math — APR and monthly rate — becomes the silent killer. Without a repayment schedule, what starts as temporary support turns into long-term cost. Many also forget servicing fees and prepayment penalties that eat any perceived savings.
Practical setup for using a loan to cover revolving credit
Start with clarity on numbers. Do this first — map outstanding balances, current APR on each card, and realistic monthly surplus. Then follow these steps:
– Calculate total cost: compare APR of revolving debts vs proposed loan rate and fees. Include origination fees and any early repayment charge.
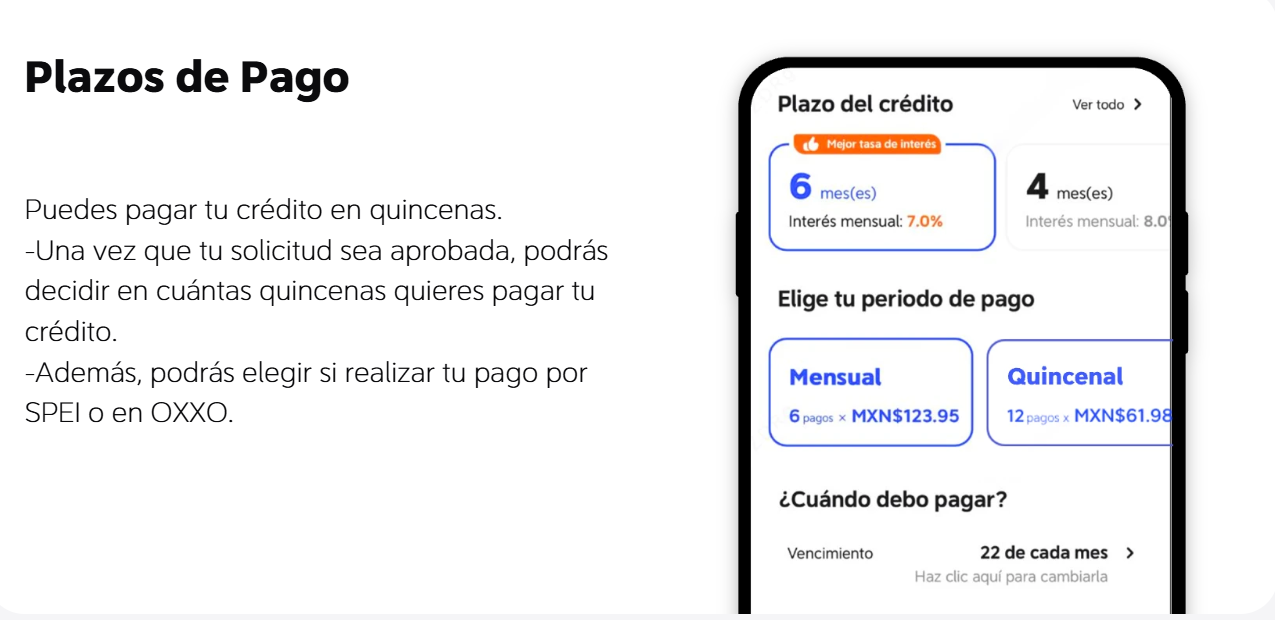
– Choose loan tenor to match repayment ability; avoid long tenors that inflate interest paid over time.
– Use direct repayment routing: route loan proceeds straight to the revolving accounts to lower credit utilization immediately.
– Set up automatic payments for the loan and freeze additional card usage until the portfolio is under control.
Watchpoints — where people usually trip up
Don’t assume lower monthly instalments equal cheaper debt. Lower monthly payment often means longer tenor and more total interest. Also watch for conditional offers that raise the effective APR after a promotional period. Collateral or guarantor requirements? Understand them fully. — A quick misread here can convert an unsecured problem into secured liability.
Alternatives to borrowing for revolving credit
Borrowing isn’t the only route. Consider these options depending on urgency and credit profile:
– Balance transfer to a 0% or low-rate card for a short term (watch transfer fees and term length).
– Personal line of credit with flexible drawdown — better if you expect recurring shortfalls.
– Employer salary advance or structured repayment — lower cost but requires agreement upfront.
– Debt consolidation loan with fixed repayment schedule — good when discipline is needed.
Quick cost example
Say you have S$3,000 on a card at 24% APR and a loan offer at 12% APR, fee 2% origination, 12-month tenor. Loan interest ≈ S$180 + S$60 fee = S$240 total extra. Card interest if you pay minimums could exceed that within months. Using the loan to clear the card reduces credit utilization and total cost — but only if you keep discipline and don’t rack up new card debt. Industry terms: APR, tenor, credit utilization.
Checklist before you proceed
– Confirm effective APR including fees.
– Ensure monthly repayment fits your budget without dipping into emergency funds.
– Lock out card use until balance is managed.
– Keep an emergency buffer equal to at least one month’s essential expenses.
Advisory close — three golden rules
1) Match tenor to repayment capacity, not to the minimum affordable instalment. 2) Compare effective APR across all options, including transfer fees and penalties. 3) Use the loan to reduce utilization immediately and enforce a strict no-new-debt rule until paid down. Follow these and you move from firefighting to control.
Real solutions come from clear numbers, a repayment plan, and discipline — and when executed well, a tailored product can be a smart part of your contingency plan. DiDi Finanzas. — practical, straightforward, and focused on keeping your balance sheet healthy.